
Traditional growth stabilisers are exhausted. Exports face constraints. Property and infrastructure have hit balance-sheet limits. So finally, the 2025 CEWC (Central Economic Work Conference) repositioned consumption as the economy’s stabiliser of last resort.
Yet Beijing’s approach remains explicitly state-led: consumption is treated as a policy object to be engineered. This sets the stage in 2026 for a shift from managing goods and transactions to planning for incomes that can support demand.
the Party points, capital flows
Advanced economies typically regard household consumption as a primary objective and driver of growth. In the PRC political economy under Beijing’s direction, consumption is not an end in itself. It is treated as an instrument of policy, managed and modulated to advance two overriding priorities: keeping the population happy and backing national industrial priorities.
The December CEWC (Central Economic Work Conference), a platform for Beijing to steady the market and reassure the public, was not a forum for debate but a vehicle for allocation and for stabilising market and public expectations—a process that which will culminate in the Government Work Report and the approval of the National Budget at the National People’s Congress in March 2026. With consumption now named a priority, directives will cascade through the system, from ministries and local governments to SOEs, banks and, ultimately, the private sector.
The tone of the December 2025 Central Economic Work Conference was more confident about the domestic baseline than in past years. At the same time, the core diagnosis has hardened. Strong supply and weak demand now form the binding constraint. That mix—greater confidence in the economy’s fundamentals alongside a more explicit demand shortfall—points to a tactical pivot towards boosting demand, not only via indiscriminate stimulus, but also through more selective ‘state engineering’ designed to determine where demand should materialise and to channel it into politically preferred products and balance-sheet repair.
the visible hand
Not waiting for any ‘invisible hand’, Beijing is going on the front foot to stimulate demand. Several distinct, state-directed toolkits are at play.
fiscal mobilisation: the state subsidises buying certain products, thereby speeding up spending decisions and boosting sales.
The ‘trade-in’ drive took shape in early 2025. By deploying C¥300 billion in special treasury bonds to cover 15 to 20 percent of the cost of certain approved consumer goods, the state used sovereign debt to soak up industrial overcapacity and pull demand forward. The scheme was endorsed at the 2025 CEWC, signalling its extension into 2026, even if the scale of bond issuance is pared back.
administrative engineering: the state defines what constitutes an ‘attractive’ new consumption sector (i.e. ‘silver economy’; ‘sports economy’; ‘low-altitude economy’, etc.), and then reallocates land, credit, subsidies, and regulatory support to ensure such products are supplied at scale.
Identifying attractive products through state mandates responds to clear directives that explicitly signal where resources should flow. When the centre designates specific ‘pilot scenarios’—such as digital immersion zones—it sends unambiguous signals about how to allocate critical inputs: investment capital, land, and credit. Firms receive an equally clear message about which goods the state wants produced. This approach operates on strictly supply-side logic: officials first determine which ‘new products’ should attract consumers, then deploy subsidies and factor allocation to guide firms toward manufacturing those predetermined goods.
The ‘Good House’ (好房子) strategy is a case in point. Formally announced at the 2025 CEWC, it positions new residential buildings as a tool to steady the property market in the wake of the now-defunct high-turnover model that threatens financial stability. Rather than stimulating demand through traditional means, officials are engineering it by fundamentally redefining ‘housing’ itself. New standards—focused on green tech, smart features, and age-friendly design—aim to create a premium asset class that will lure reluctant buyers and thaw trapped liquidity. Beyond steadying the market, the strategy is designed to generate spillover by turning housing into a consumption sink for downstream sectors, including smart-home devices and low-carbon building materials.
‘planning’ incomes
While the engineering mindset remains constant, the target of that engineering is undergoing a fundamental shift in 2026. The state realises it cannot engineer consumption indefinitely if the fuel, income, is low.
The retreat from consumer goods and appliances is evident in the policy language. In 2024, the keyword for trade-ins was ‘expand’ (加力). In 2025, it softened to ‘optimise’ (优化). This shift suggests Beijing is acknowledging the fading returns from simply subsidising physical goods.
A shift toward ‘human infrastructure’ shows a move to invest more in people. The CEWC highlighted a key message: combine investment in things with investment in people.
The principle is not to embrace Western welfarism. Rather, the population is treated as ‘human capital infrastructure.’ Income transfers and social-security reforms are now viewed as essential upkeep to keep the workforce—and the industrial machine—running.
This principle is on display in the 2025 order to ‘formulate and implement a resident income increase plan’ (制定实施城乡居民增收计划). The word ‘plan’ (计划) is decisive. In the CCP’s political lexicon, a ‘plan’ lifts income growth from a vague aspiration to an enforceable government mandate. The evolution of CEWC language confirms this structural shift:
2022–23: vague slogans (multi-channel increase)
2024: specific but narrow (pensions)
2025: ‘formulate and implement a plan…’ — marking the start of a systematic, long-term, and broad campaign to upgrade the nation’s human capital
To boost consumption, Beijing is doubling down on state direction rather than easing it. The move toward an ‘income plan’ marks a redirection of state resources—from following Say’s Law, that ‘supply creates demand’, to recognising that real growth depends on putting money in consumers’ pockets and improving social services. Even so, consumption will remain a state-managed project—driven by the national interest and leveraged to propel the PRC up the tech, green, and innovation ladder.
party-line thinkers
Lin Yifu 林毅夫 | Peking University National School of Development president emeritus
To revive the economy, Lin advocates vigorous state intervention through active fiscal policies, challenging the theoretical constraints of Ricardian equivalence. He argues that government-led investment in infrastructure does not crowd out private spending; rather, it serves to boost consumption.
By financing large-scale projects—often executed by SOEs—the government creates employment, which in turn raises household income and thereby generates consumer demand. This approach utilises a ‘facilitating government’ to overcome market failures, ensuring that state spending effectively translates into wage growth and sustainable economic expansion. Lin’s perspective represents Beijing’s traditional approach: driving domestic demand and economic growth through state investment in large-scale projects.
Lin Yifu 林毅夫 is an influential PRC development economist and the founder of ‘New Structural Economics’. Liu systematically argues for the positive role of the state in industrial upgrading, infrastructure and market development. He previously served as a member of the Chinese People’s Political Consultative Conference Standing Committee, a policy adviser to multiple State Council ministries, and a senior vice president and chief economist at the World Bank. His policy views have directly shaped the long-term direction in PRC supply-side structural reform, regional coordination, industrial policy and the ‘effective market and proactive government’ model.
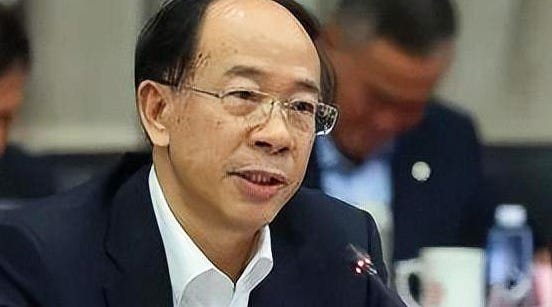
Yin Yanlin 尹艳林 | CPPCC 14th National Committee economic committee deputy director
To bridge the consumption gap with advanced nations, Yin argues that the government must actively intervene by carrying through ‘urban and rural resident income increase plans.’ He notes that boosting consumption is not merely a market function but requires improving income distribution through tax optimisation and increased transfer payments. Furthermore, Yin advocates for active fiscal policies, suggesting that state investment should be redirected to ‘combine investment in things with investment in people.’ By improving public services and social security, the state effectively removes the anxieties that suppress spending, thereby using state spending to engineer a sustained recovery in consumer demand.
Yin signals a change in direction from Lin Yifu’s opinions, which focus on plans to grow individual incomes. However, his approach shares the same underlying logic: the state raises income through planning mechanisms rather than relying solely on the market economy.
Yin Yanlin is a distinguished PRC economist and senior policymaker. He served at the National Development and Reform Commission for 15 years, where he notably spearheaded the PRC’s first government White Paper on income distribution. He subsequently joined the Office of the Central Financial and Economic Affairs Commission, rising to the position of Deputy Director (2017–23). During his tenure, he was instrumental in drafting key documents for multiple Central Economic Work Conferences, directly shaping national strategies on economic development and wealth distribution. Since 2023, Yin has served as Vice Chairman of the Committee on Economic Affairs of the 14th CPPCC National Committee.
context
19 Dec 2025: State Council executive meeting on arranging the Central Economic Work Conference
18 Dec 2025: uneven recovery marks China’s PV industry ‘anti-involution’ progress
17 Dec 2025: ‘lowest price across the web’ may constitute abuse of dominance
13 Dec 2025: NDRC explains ‘cross-cyclical adjustments’ and its implementation
11 Dec 2025: 2025 Central Economic Work Conference
03 Dec 2025: PRC economic adviser believes that an AI bubble in the US may burst during the 15th 5-year plan period
02 Dec 2025: PRC economic adviser suggests manufacturing share of the PRC’s GDP should not fall below 25 percent
This distinction between treating consumption as a policy object and treating it as household purchasing power is very useful. The gap becomes especially important for services: supply-side support can build capacity, but it cannot substitute for households having the income and confidence to demand the services being built.
Common beliefs I used to read were that people were literally savers, and that health services and pensions were drivers for saving. Both however are strong contenders for direct fiscal policy if the social democratic west offers a kind of unthinking common sense norm, and historically the Soviet bloc countries.